The laziest argument about Indian electronics manufacturing comes in two versions. Government cheerleaders say almost every phone sold here is made in India, therefore the mission is accomplished. Cynics reply that factories merely screw imported parts together, therefore nothing has changed. Both positions save their owners from examining a complicated industrial transition. India’s mobile-manufacturing policy has produced real scale, exports and employment. It has not yet secured enough domestic value in components, machinery, design or intellectual property.
The government’s April 2026 PLI assessment says domestic value addition in electronics had reached roughly 18–20 per cent and reports production, exports and direct employment under the large-scale electronics scheme. A separate PIB account of the wider sector acknowledges the continuing electronics trade gap while describing the component-manufacturing push. Those two facts belong in the same sentence: India has become a serious assembly and export base, and it remains dependent on imported high-value inputs.
Assembly was a necessary first rung
I have little patience for people who use the word assembly as an insult. Every electronics power began by learning production disciplines, supplier coordination, quality control and export logistics. A country does not jump from importing finished phones to fabricating advanced chips and designing global brands in one policy cycle.
PLI worked because it offered a measurable incentive tied to incremental output. It helped offset disadvantages in logistics, taxation and supply-chain depth. Global manufacturers responded because India combined a huge domestic market with the possibility of export scale. That is a policy achievement, not an accident.
It is also fair to credit consistency. Industrial policy fails when governments change rules mid-investment or spread small subsidies across fashionable sectors. The mobile scheme had a clear anchor product and attracted suppliers around it. Plants employing thousands of workers, many of them women entering formal manufacturing, matter beyond spreadsheet nationalism.
Value addition is the harder phase
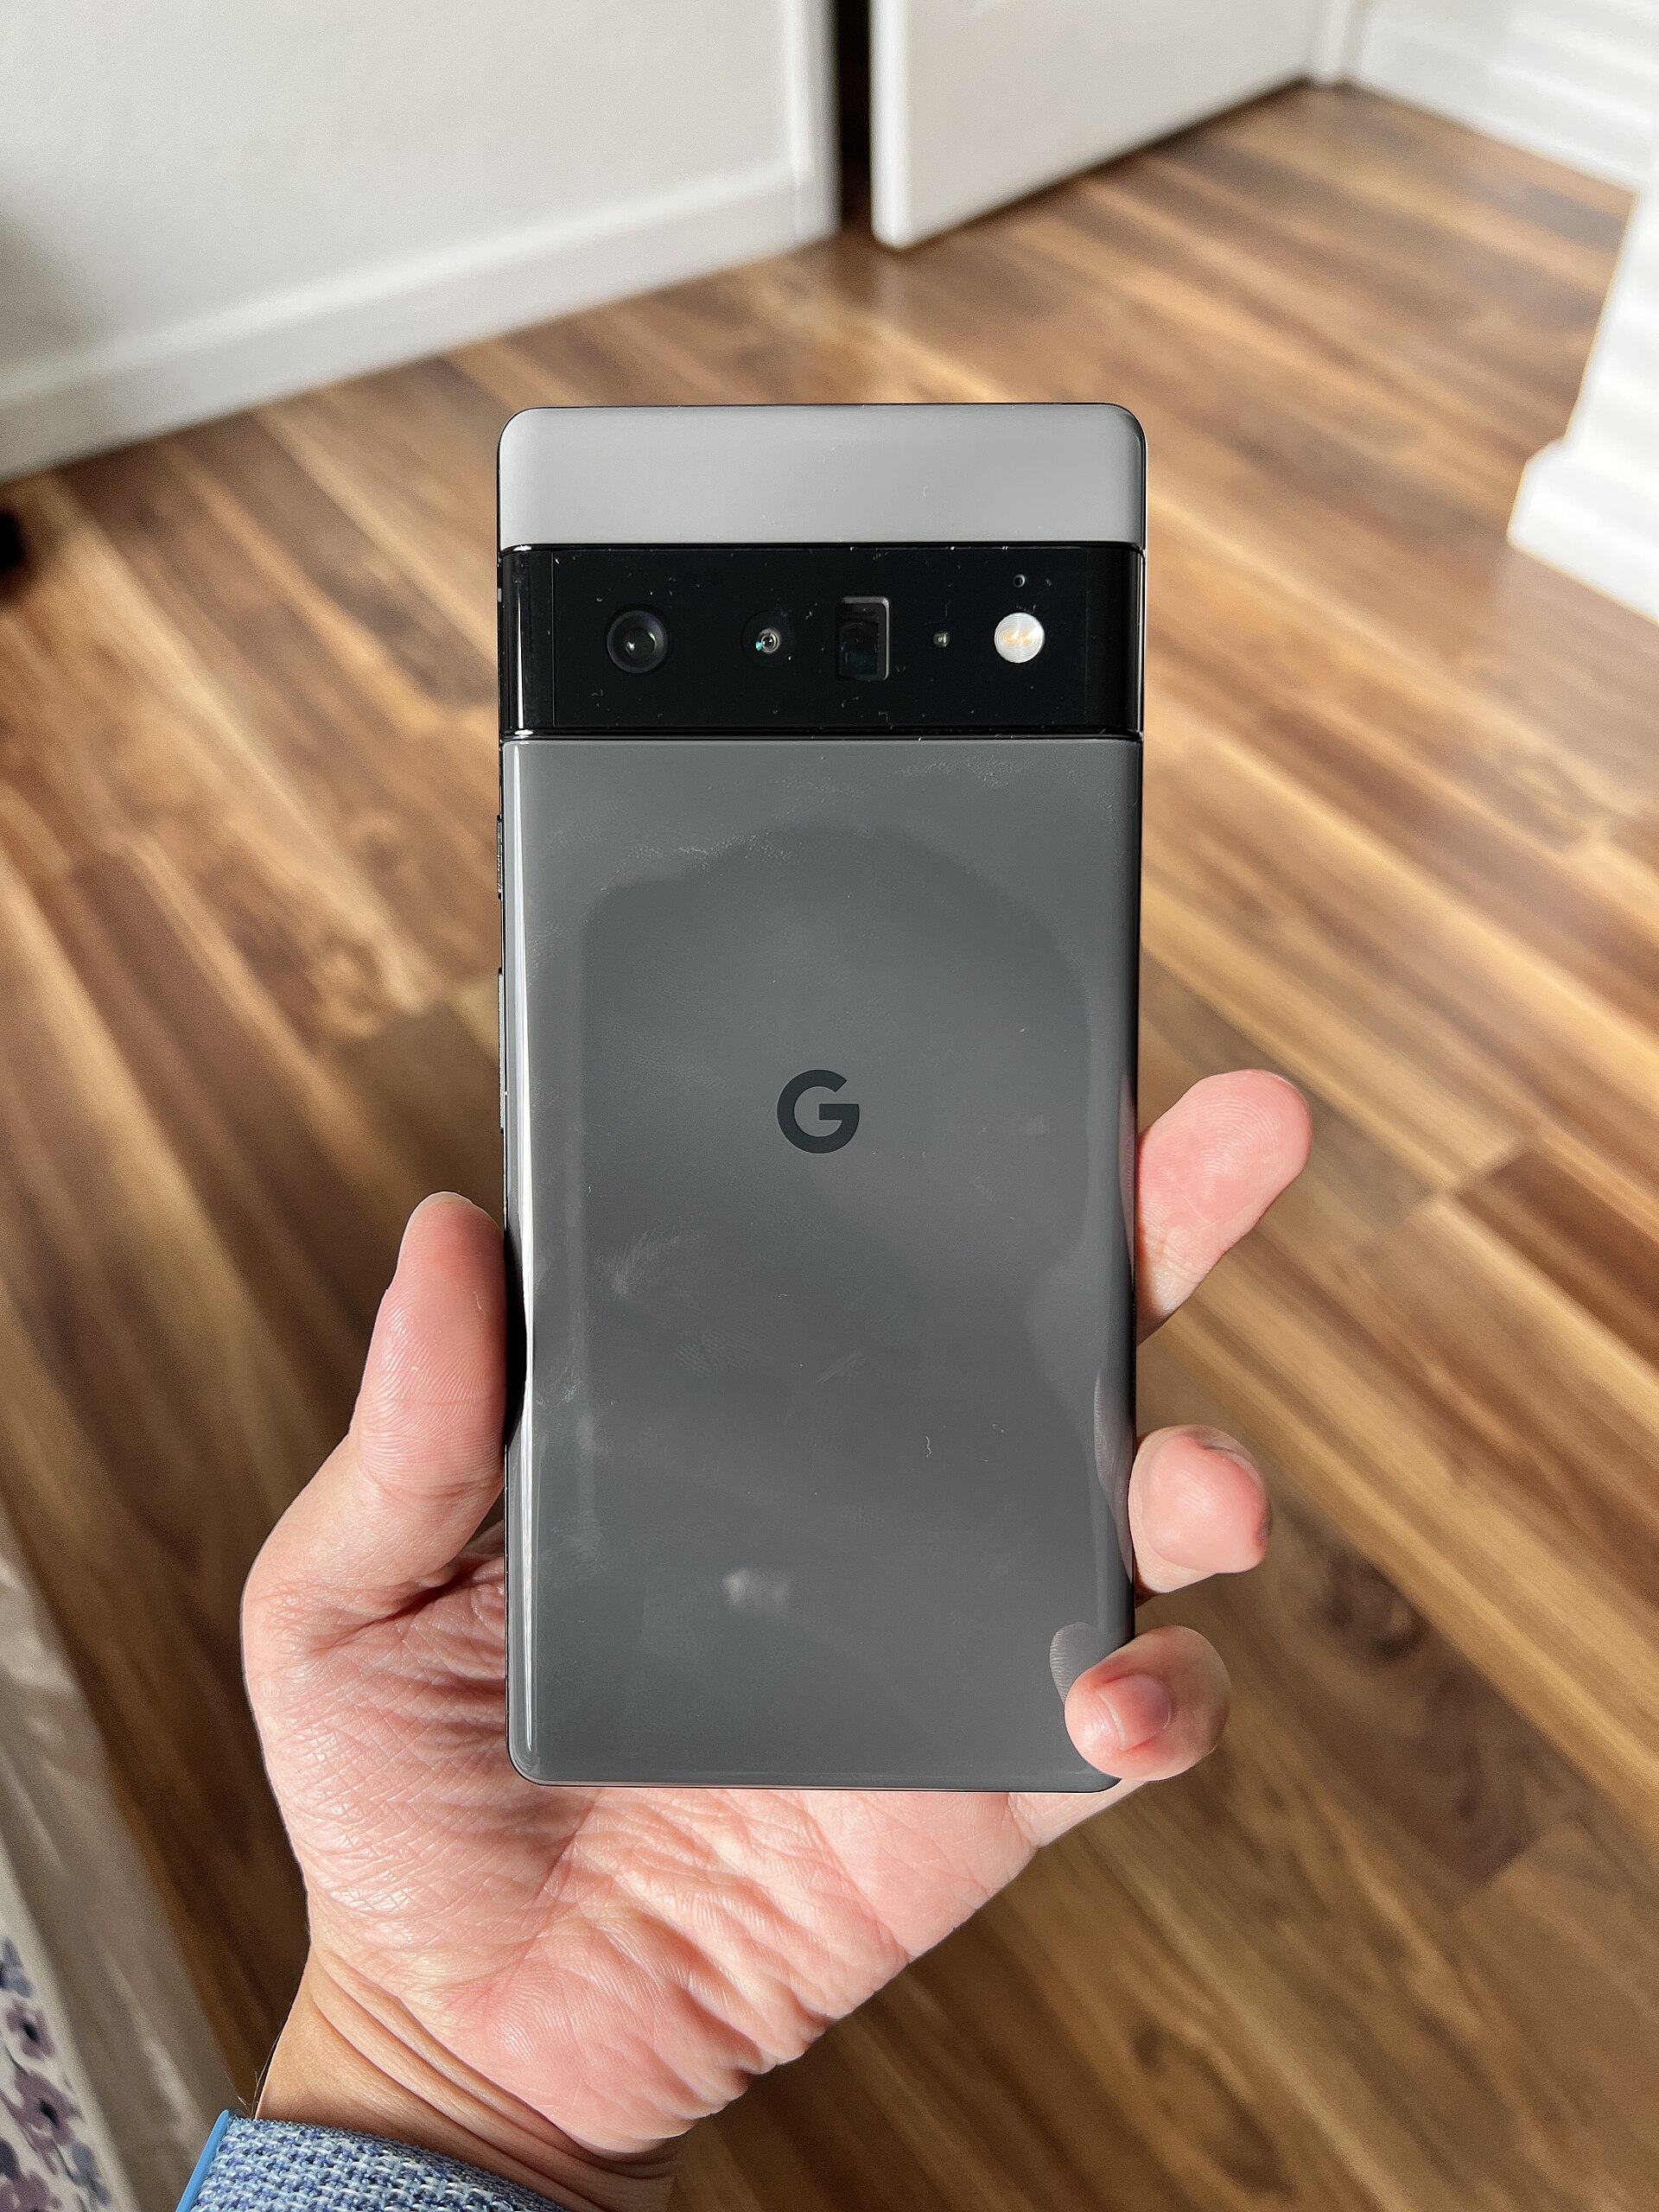
The bill of materials inside a smartphone is uneven. The display, processor, memory, camera modules and radio components capture far more value than packaging or final assembly. India can export billions of dollars of phones while importing much of what makes those phones expensive. Gross export figures therefore cannot be the only success measure.
The components scheme must be judged by whether it creates competitive suppliers after incentives fade. Printed circuit boards, enclosures, batteries, camera modules and passive components offer different technological and capital barriers. Policy should publish category-level domestic value addition and distinguish Indian value from parts merely routed through an Indian invoice.
Semiconductors are even more demanding. Fabrication plants require capital, power, water, specialised chemicals, equipment service and engineering talent. Political announcements cannot compress the learning curve. India should resist the temptation to count every memorandum as capacity. Packaging, testing, compound semiconductors and design services may deliver earlier gains while large fabs mature.
Why Chinese brands still dominate
Chinese smartphone brands remain powerful in India because they built distribution, pricing discipline, fast product cycles and service networks. Nationality is not a substitute for execution. An Indian logo on a mediocre phone will not persuade a buyer spending several months of savings.
These companies also understand segmentation. They know which camera, charging speed or storage tier will move a ₹20,000 device. Their supplier relationships let them combine features at prices domestic challengers struggle to match. Policy can correct structural disadvantages; it cannot manufacture product judgment.
Indian brands need patient capital, design talent and credible after-sales service. White-labelling a generic device and wrapping it in patriotic advertising is not industrial strategy. The opportunity may begin in specialised segments—rugged devices, enterprise hardware, education tablets, automotive electronics or secure government products—before a mass-market flagship.
The next scorecard must be less flattering
I want the government to publish a tougher annual scorecard: net foreign exchange earned, domestic value added by component, research spending, patents commercialised, supplier survival after incentives and median wages. Production and export totals should remain, but they should no longer be allowed to carry the whole argument.
Incentives should decline predictably as scale improves. Permanent subsidy creates factories skilled at lobbying rather than manufacturing. Support can shift toward shared testing facilities, engineering education, customs stability and logistics—the public goods that help many firms.
Labour quality matters too. Assembly jobs are valuable, but India should create paths from operator to technician, engineer and production manager. Firms receiving public incentives should report training outcomes and workplace conditions. Industrial policy gains legitimacy when workers acquire durable skills, not only when companies hit shipment targets.
A success worth making harder
The mobile PLI scheme disproved the fatalistic claim that India cannot manufacture at scale. That is substantial. It also created the platform from which more difficult questions can be asked. How much value stays here? Who designs the product? Which Indian supplier can sell to several global brands without an incentive?
The government deserves credit for the first phase and pressure on the second. The opposition’s reflex to dismiss assembly ignores how supply chains develop. Official self-congratulation risks the opposite mistake: treating the first rung as the destination.
India now makes phones in volumes that were implausible a decade ago. The next ambition is not to replace one slogan with another. It is to build an ecosystem capable of designing components, maintaining machinery and owning technology. The box can say made in India; the balance sheet must increasingly explain what that means.