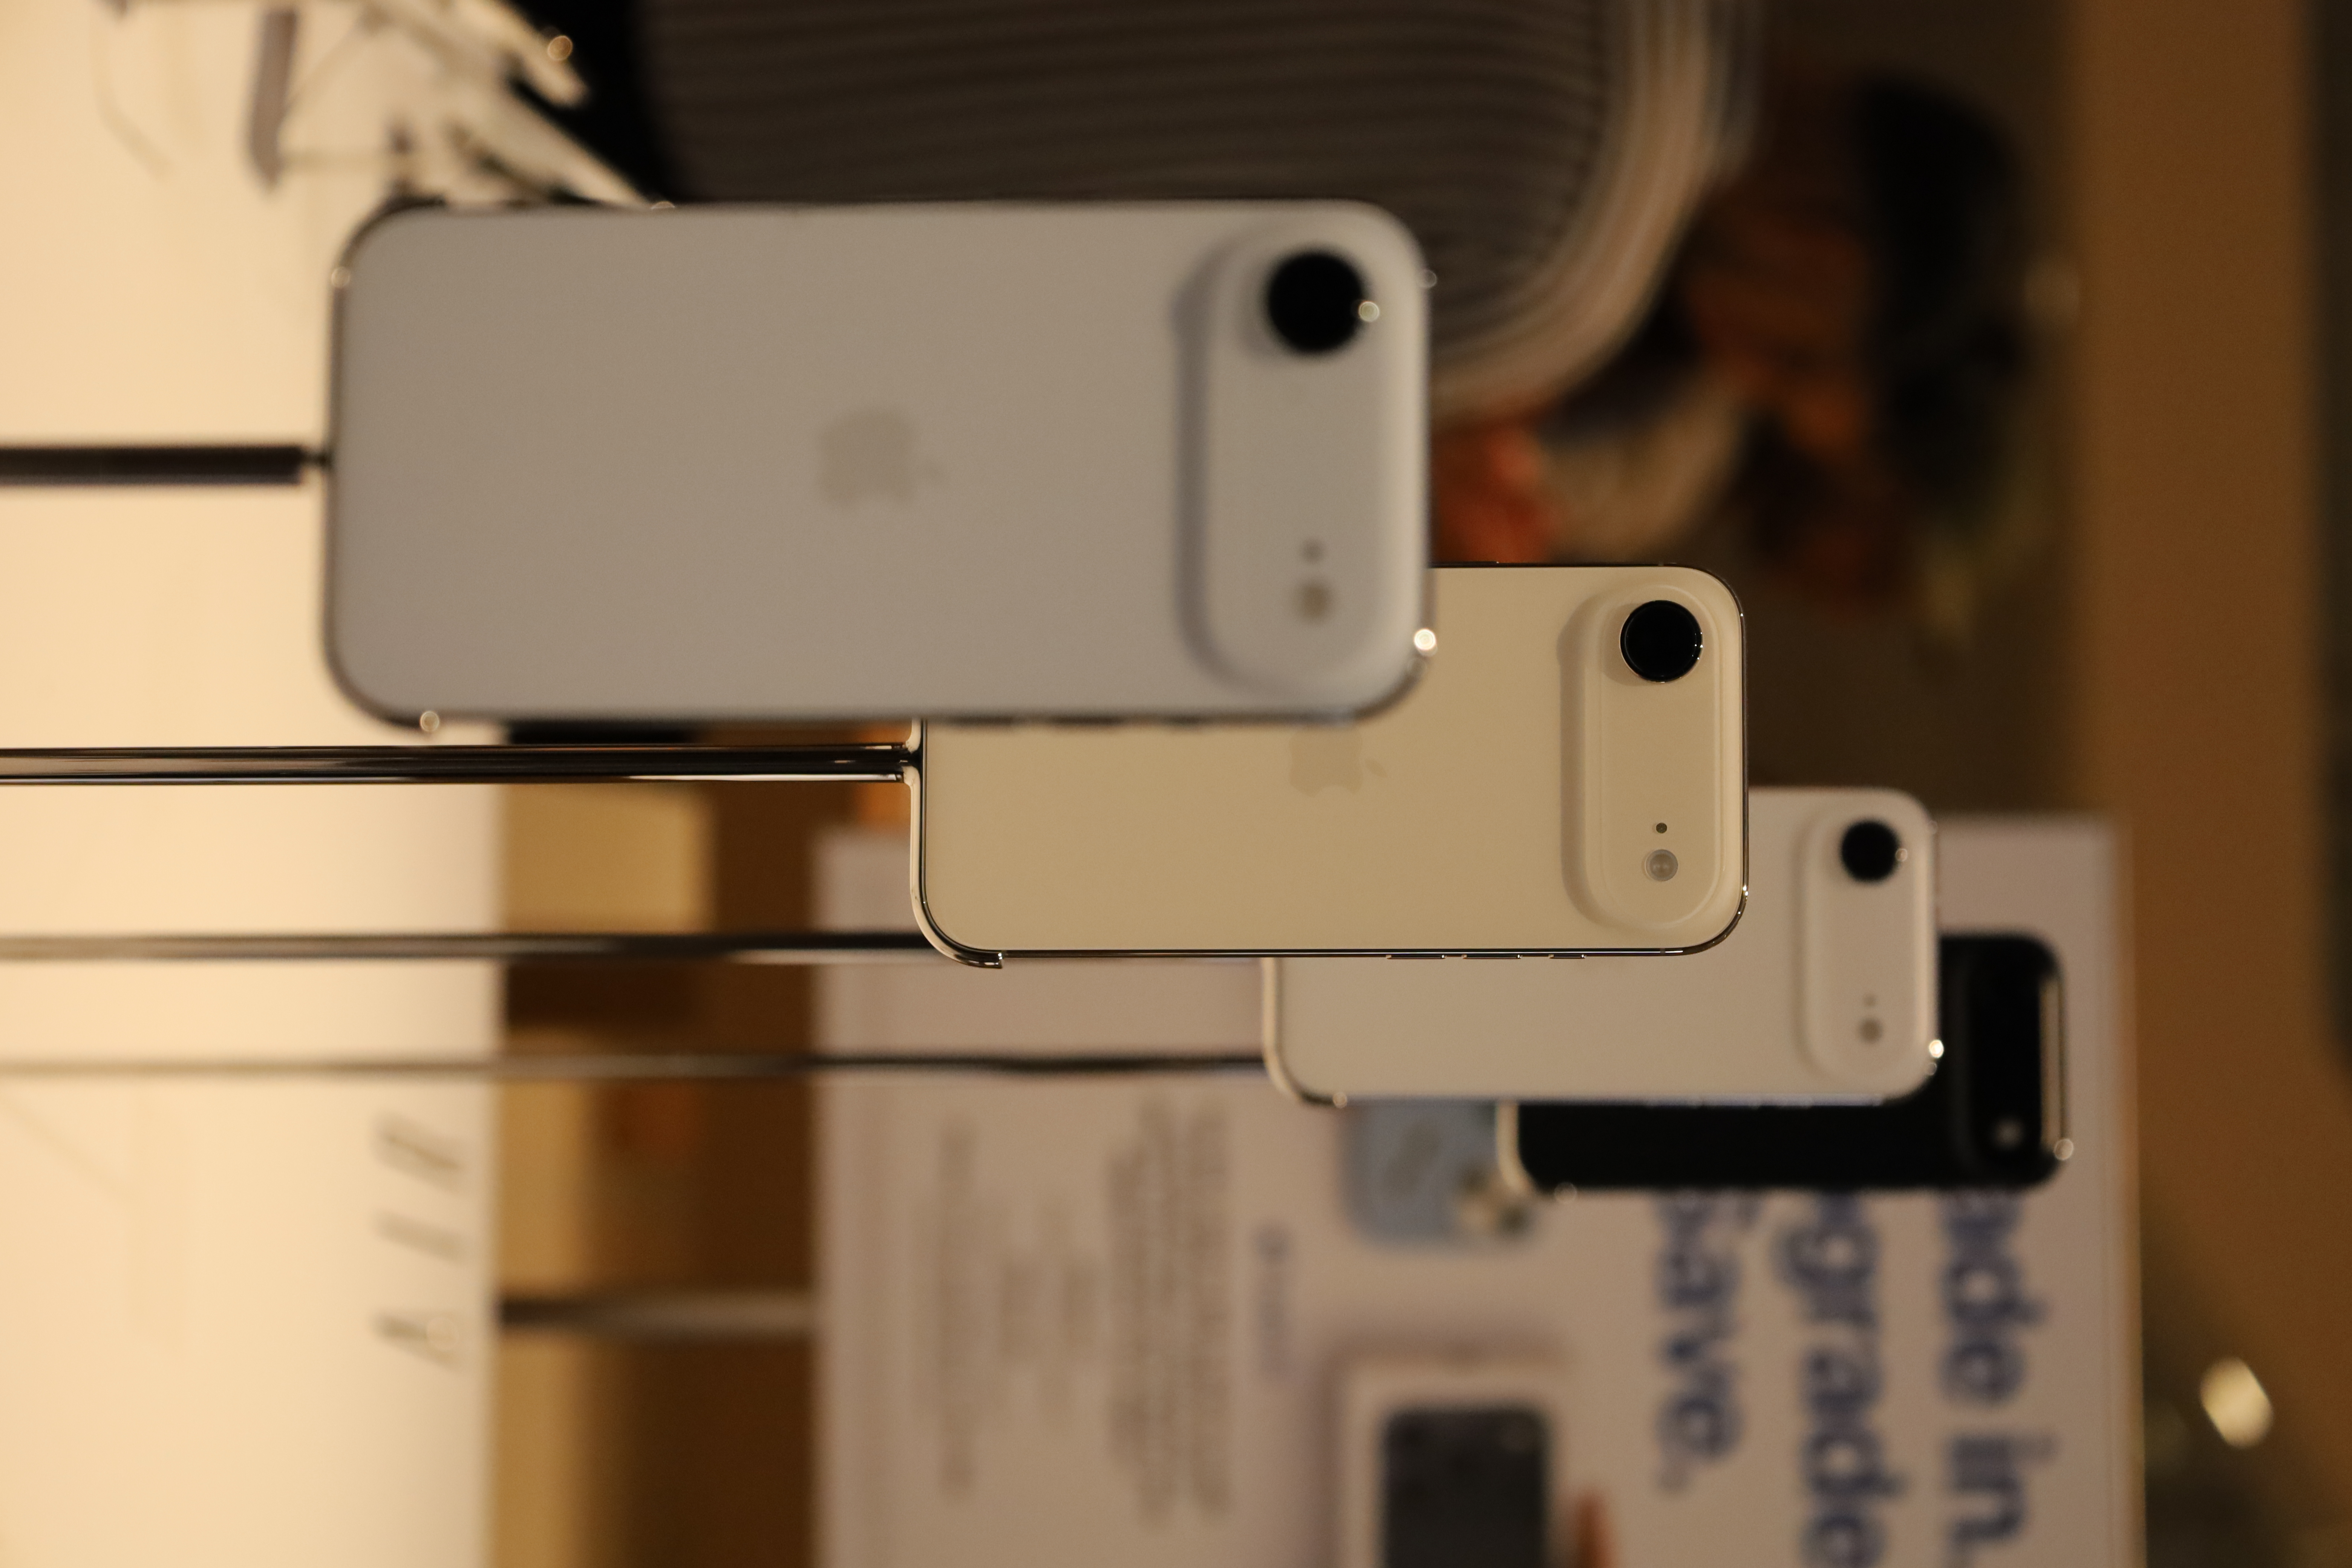
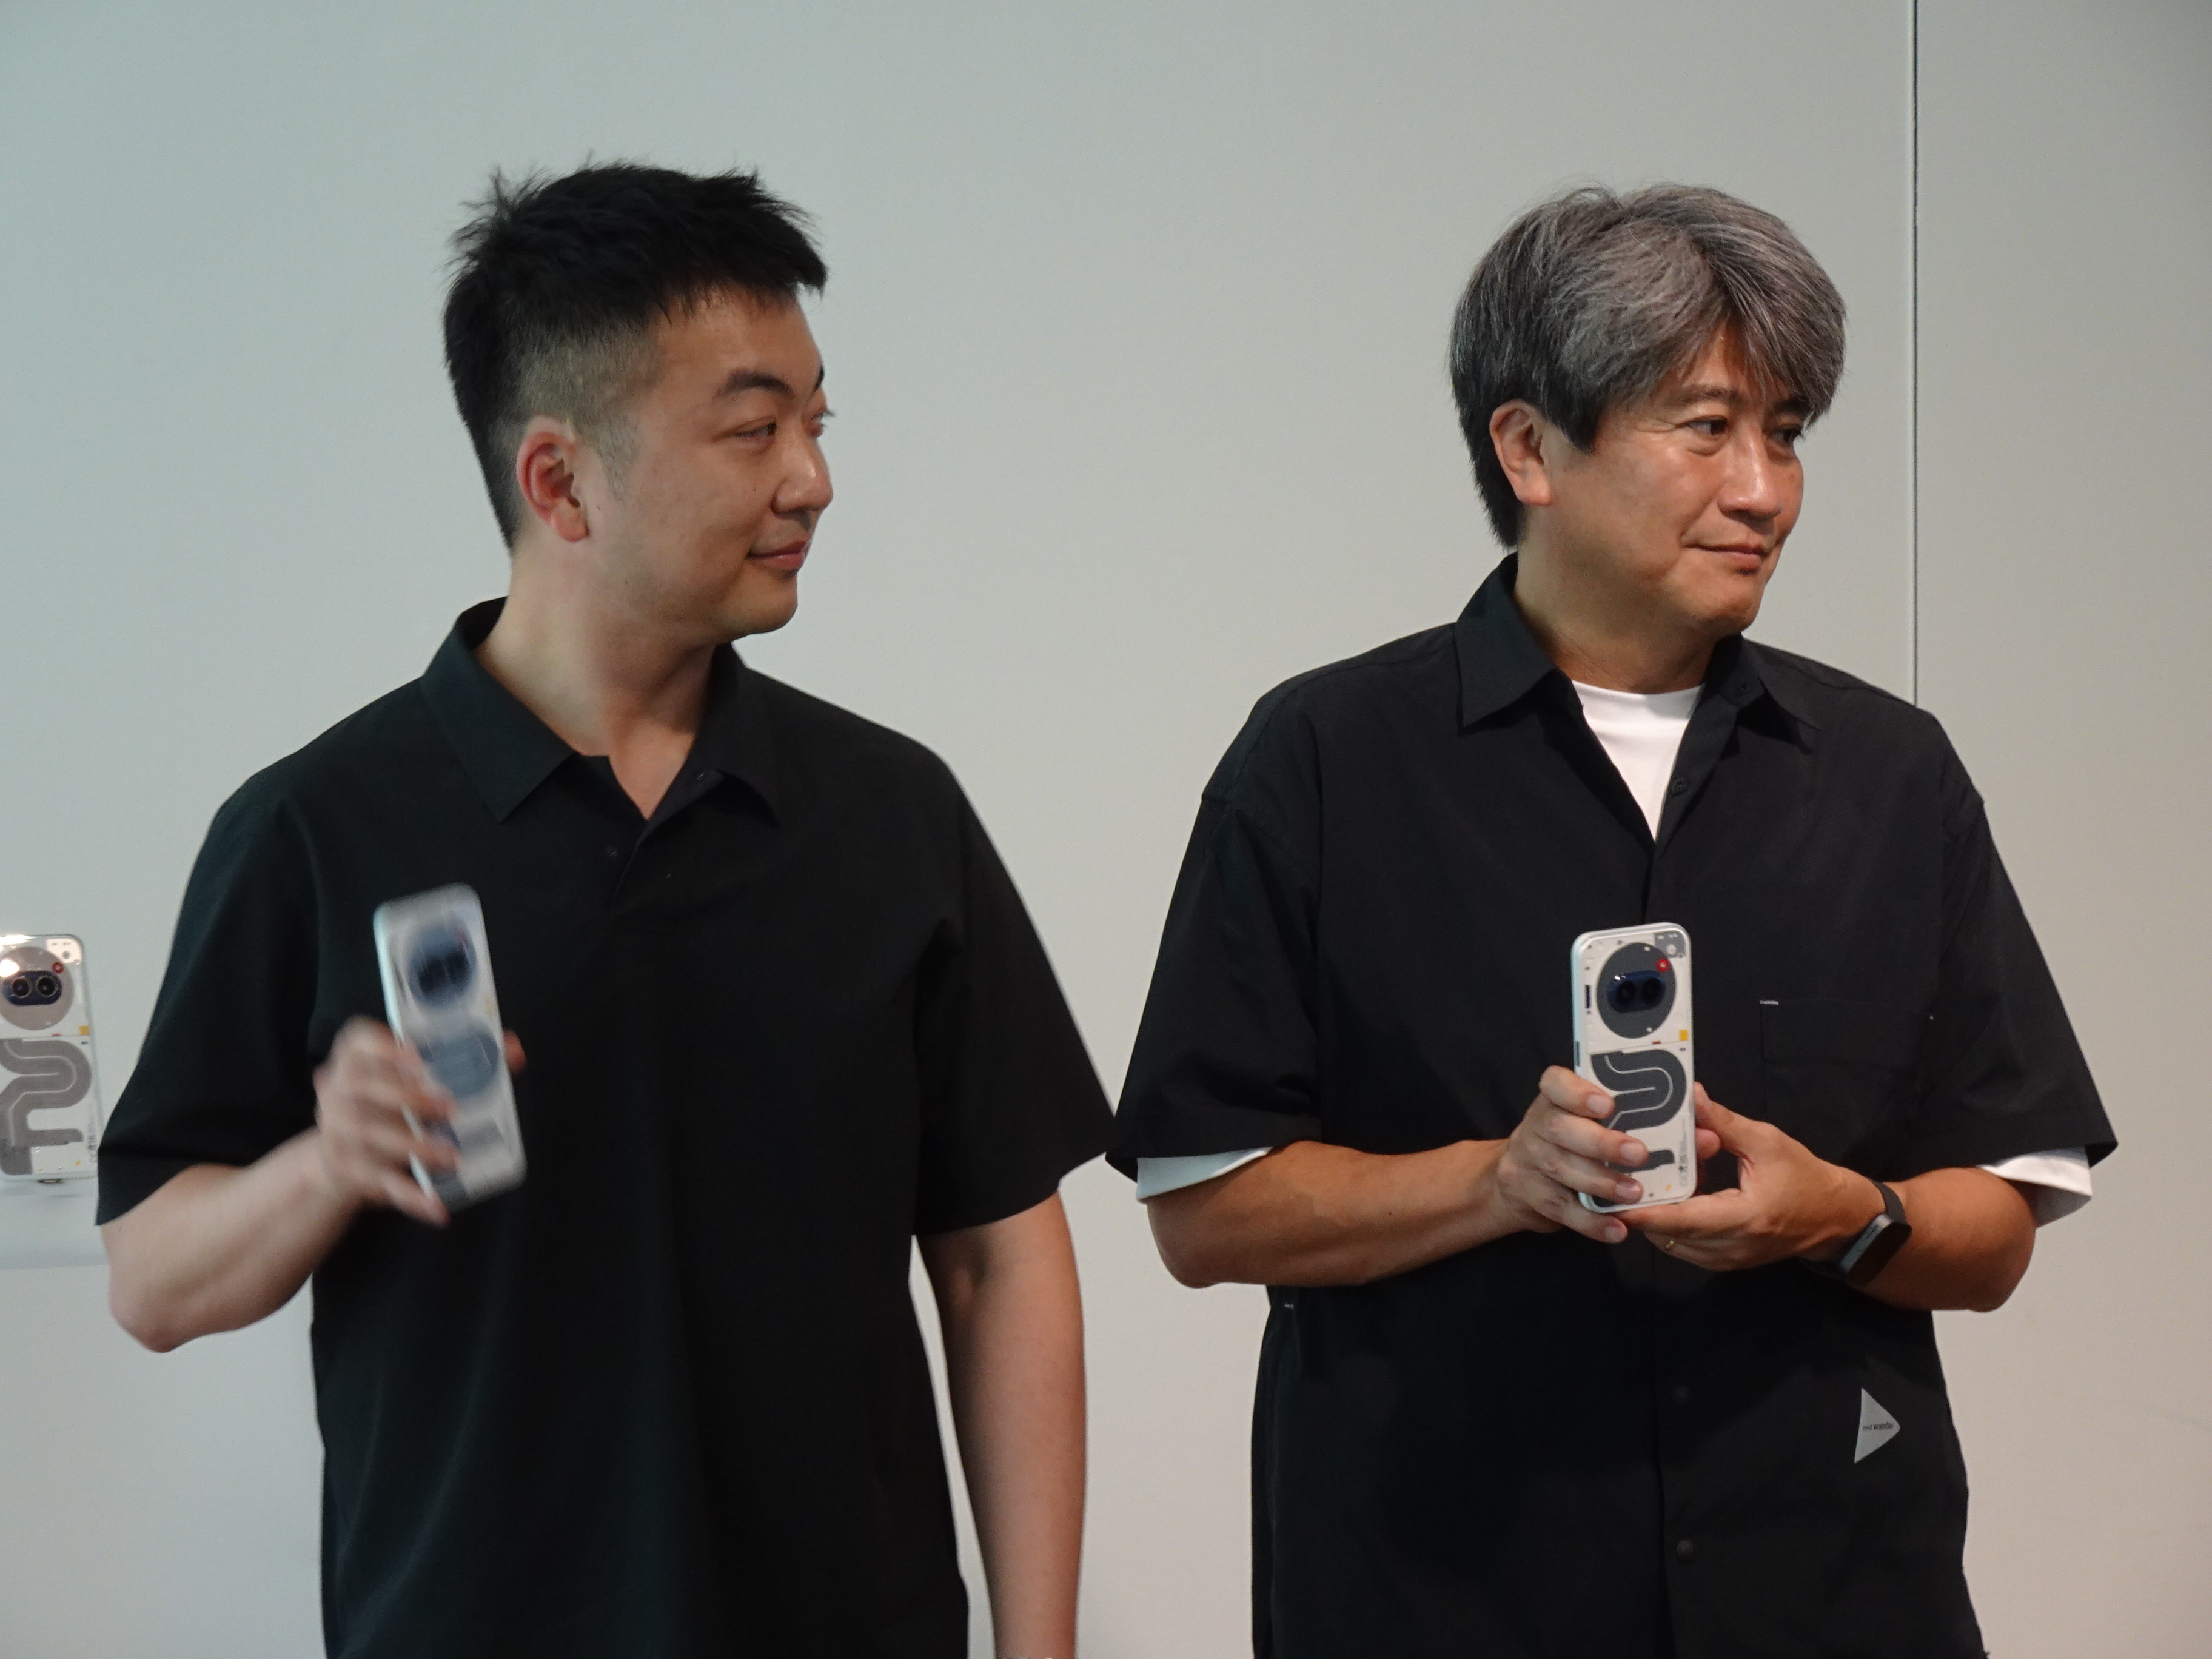
Nothing says it plans to launch more than twice as many smartphones next year, and the predictable response is excitement about choice. I see a warning label. The Indian phone market does not suffer from a shortage of model names. It suffers from shallow domestic value addition, short product lives and consumers being asked to decode families full of tiny differences. Nothing has built a recognisable design language and an unusually engaged community. Those are achievements. But a rapid expansion from a small line to more than six phones risks turning distinctiveness into catalogue management. It also illustrates a persistent confusion in our electronics debate: a company can assemble more devices in India without India capturing the difficult, profitable layers of the supply chain.
More launches are a commercial plan, not industrial policy
The company’s roadmap was reported by Gadgets 360, which noted that Nothing released three phones in India in 2026 and now intends more than twice that number. The company also plans community previews through a co-creation programme in Delhi. Its broader product history is collected on the outlet’s Nothing brand page. None of this is objectionable. It is simply not evidence that India is moving from assembly to electronics capability.
When a phone box says made in India, consumers reasonably imagine Indian factories creating much of the device. In practice, the phrase can cover very different realities. Final assembly and testing generate employment and build operational skill. They are worth encouraging. But the display, memory, processor, camera sensors and many precision components may still come from overseas. The value retained in India depends on tooling, supplier ecosystems, engineering and intellectual property, not the patriotic enthusiasm of the launch event.
Nothing is hardly alone. Chinese brands dominate Indian sales because they combine supply-chain scale, distribution, pricing and rapid product cycles. They understand the market’s appetite for visible specifications and channel incentives. Indian policy has helped attract assembly, but it has not magically erased their advantages. If a British-headquartered brand expands models using many of the same Asian component networks, the competitive logo changes faster than the industrial structure.
India should demand a value-addition ladder
Government incentives need public milestones beyond unit output. What share of the bill of materials is sourced locally? Which components moved from import to domestic production? How many supplier engineers were trained? Are locally assembled phones exported? Did the company conduct hardware validation or software optimisation in India? These questions should be answered in comparable formats, with commercially sensitive details protected but broad claims auditable.
The first rung is assembly. The next includes enclosures, chargers, cables, packaging, printed-circuit-board assembly and mechanical parts. Higher rungs involve displays, camera modules, batteries, advanced semiconductors, product design and manufacturing equipment. No sensible person expects every component to become Indian immediately. The problem is policy language that celebrates the first rung as though the ladder has been climbed.
Nothing’s design identity could create opportunities for Indian engineering if the company chooses. Distinctive transparent housings, lighting systems and accessory ecosystems require mechanical tolerances and testing. It could develop local suppliers, conduct reliability engineering here and export India-built models. A Delhi community event is pleasant; a supplier-development centre would be consequential.
The company should also resist fragmenting software support across too many devices. Doubling launches multiplies camera tuning, carrier certification, update testing and spare-parts inventory. Larger manufacturers struggle with this. A young company risks stretching its engineering organisation while marketing celebrates momentum. If older Nothing phones receive slower patches because six successors require attention, expansion will have transferred cost to loyal buyers.
Chinese brands dominate for reasons slogans cannot solve
Policy discussions sometimes imply that Chinese brands retain share because Indian consumers are insufficiently patriotic. That is insulting. People buy phones that fit budgets, are available nearby and offer useful features. Chinese firms invested in retail relationships, service networks and product planning. They frequently overproduce models and preload unwanted software, but they also respond quickly to price segments. Consumers do not owe any company a handicap.
To compete, India needs supplier density. A component maker locates where it can serve several customers, access skilled labour, obtain reliable power and move goods efficiently. That means industrial policy must support clusters rather than isolated assembly announcements. Customs rules should be stable enough for investment decisions. Testing labs, logistics and technical education matter as much as subsidies.
There is a difficult balance between protecting emerging local production and raising device prices. High import duties can encourage assembly while making components expensive and reducing export competitiveness. Policy should reward increasing value addition rather than merely penalising finished-device imports forever. The goal is not a sheltered market producing costly phones; it is an Indian base capable of competing globally.
Nothing’s international brand could help. If India becomes a manufacturing and engineering hub for global shipments, volumes can justify deeper localisation. If factories serve only domestic demand, the supplier case is weaker. I want the company to publish export ambitions alongside launch counts.
Community is useful, but it is not co-ownership
Nothing has been clever about community. Fans feel involved in the brand’s design conversation, and early previews can uncover bad ideas. Yet companies should be precise about co-creation. Users offering feedback do not choose suppliers, control update budgets or share profits. Community language can become unpaid market research wrapped in belonging.
The Delhi programme should publish what changed because of participant input. Did a button move, an accessibility feature improve or a colour get rejected? Closing the feedback loop would make the exercise meaningful. Otherwise, a sneak peek is simply a small launch event with better intimacy.
Indian consumers should ask ownership questions during these sessions. How many years of security patches? Are batteries and screens stocked locally? Will repair manuals and prices be public? How much preloaded software can be removed? A phone is not made more Indian because its marketing listens in Delhi while its after-sales decisions are made elsewhere.
I do not object to Nothing launching more phones. Competition may lower prices and extend its clean software to more segments. I object to interpreting quantity as maturity. A coherent range of three well-supported devices can create more value than seven lightly differentiated ones. Product restraint is an industrial virtue because it concentrates engineering, parts and software effort.
Make in India should be judged through learning that remains after a model is discontinued. Did workers acquire transferable skills? Did suppliers gain processes they can sell to other manufacturers? Did local teams own design decisions? Did exports become viable? Those are durable gains. Launch calendars disappear into archive pages.
Nothing has an opportunity to show that a newer brand can grow differently: fewer meaningless variants, deeper local engineering, transparent support and a supplier plan tied to exports. If it simply doubles model names, it will be following the same volume logic that made the market exhausting. India does not need another company proving that phones can be screwed together here. It needs companies proving that increasingly complex parts, processes and ideas can originate here too.