There is a familiar Delhi ritual whenever the Modi government simplifies something. First, the reform is declared impossible. Then, when it happens, the commentariat says it was obvious and overdue. Finally, Congress politicians claim they always wanted precisely this version, preferably without mentioning the years in which their own coalition could not assemble it. The cleaner GST structure belongs in that pattern. I do not regard every tax-rate change as an economic revolution, and I am wary of government slogans that turn household arithmetic into a festival. But moving toward fewer principal slabs, reducing classification disputes and easing rates on widely used goods is real reform. The right response is neither devotional applause nor opposition sneering. It is to recognise the gain, then insist that the tax administration match the simplicity promised by the rate card.
India finally chose intelligibility
The official GST Council recommendations set out a structure centred on 5 and 18 per cent rates, alongside a higher rate for specified luxury and sin goods. They also included process measures on registration, refunds and the appellate system. One may debate individual classifications, but the direction is correct. A consumption tax should be broad, legible and difficult to game. The old thicket of rates invited businesses to spend energy proving that a product belonged in one semantic box rather than another. That is not sophisticated policymaking. It is a national parlour game conducted with invoices and litigation.
Congress’s criticism would carry more weight if it were accompanied by an alternative design rather than ritual accusations of favouring the rich. The party often treats complexity as social justice because complicated systems allow its spokespeople to announce finely targeted concern. In practice, complexity rewards firms that can retain tax lawyers and punishes small manufacturers that cannot. A proprietor in Coimbatore, Surat or Ludhiana does not experience a classification dispute as an ideological seminar. She experiences blocked working capital, notices, professional fees and weeks spent explaining a product to officials. Simpler slabs are therefore not a corporate indulgence. They are particularly valuable to businesses without a compliance department.
The reform also deserves historical honesty. GST was discussed before 2014, and state governments of different parties helped shape it. The BJP cannot claim to have invented every idea embedded in the tax. But ideas do not collect revenue; implemented systems do. The Modi government spent political capital to launch GST, absorbed the deserved criticism of a rough initial rollout, built the digital plumbing and kept negotiating changes through the Council. Congress nostalgia selectively remembers the proposal and forgets the paralysis. It wants authorship without accountability: credit for imagining a national tax, immunity for failing to deliver it and permanent licence to mock those who did.
The strongest case is the record, not the slogan
A government nine-year GST assessment reports a substantially expanded taxpayer base and continued growth in collections. Those are official claims and should be scrutinised rather than treated as scripture. Yet the broad change is undeniable: India now operates a common indirect-tax framework supported by digital invoices, returns and interstate credit. Trucks no longer spend the same absurd hours at internal tax barriers, and firms can plan distribution across a national market. We have become so accustomed to that improvement that critics discuss GST as though it were merely a row over whether shampoo belongs at one rate or another. Administrative normality has concealed the scale of the earlier fragmentation.
I also understand the counterargument. A tax collected efficiently can still burden households, and headline rate cuts do not automatically reach retail prices. Businesses may preserve margins, supply chains may adjust slowly and consumers rarely receive a neat receipt saying how much reform saved them. The government should not answer this with moral lectures about patriotic shopping. It should publish price-monitoring evidence, strengthen competition and avoid threatening every merchant who cannot instantly reprint a catalogue. Pass-through happens through market pressure as well as enforcement. Ministers should resist turning a sensible tax reform into another television hunt for villains.
Nor is a two-slab headline the same as a simple system. Exemptions, cesses, special rates and interpretive circulars can recreate complexity beneath an elegant poster. India has a bureaucratic talent for removing one form and inventing three clarifications about its absence. The next stage must therefore be measured by disputes avoided, refunds completed and hours of compliance saved. I want the GST Council to publish a yearly complexity audit: number of active rate categories, average refund time, pending appeals, contradictory advance rulings and compliance cost for firms at different turnover levels. If the dashboard worsens while collections rise, the administration is extracting more efficiently but governing no better.
Small business needs certainty more than sympathy
The most important promises concern refunds and registration. Exporters and firms caught in inverted-duty structures effectively lend money to the state when legitimate credits remain stuck. Large companies can finance the delay; small ones cancel orders, postpone wages or borrow at painful rates. Risk-based provisional refunds can improve cash flow, provided the risk engine is transparent enough to challenge and does not quietly blacklist entire sectors. Automated registration for low-risk applicants is similarly welcome. But automation must have a human escape hatch. A computer that approves quickly is useful; a computer that rejects inexplicably is merely a babu with better uptime.
The appellate architecture also matters. For years, businesses faced uncertainty because the promised tribunal system was incomplete. Tax policy becomes arbitrary when an assessee can technically appeal but lacks a functioning forum. The government deserves credit for pushing operationalisation, and it deserves continued pressure to fill vacancies, publish disposal data and prevent backlogs from becoming permanent. A reforming state is not one that never creates disputes. It is one that resolves them predictably before uncertainty becomes a business model for intermediaries.
I would go further and require every new GST clarification to include a plain-language example, an effective date and an explicit statement about whether past transactions will be reopened. Retrospective anxiety is corrosive. Entrepreneurs can manage a known tax; they cannot sensibly price the risk that an ordinary interpretation will be declared wrong three years later. The Council should also establish a binding mechanism to reconcile conflicting state-level rulings. “One nation, one tax” sounds rather thin when the same product acquires different meanings after crossing a state border.
Credit the reform, then demand the boring work
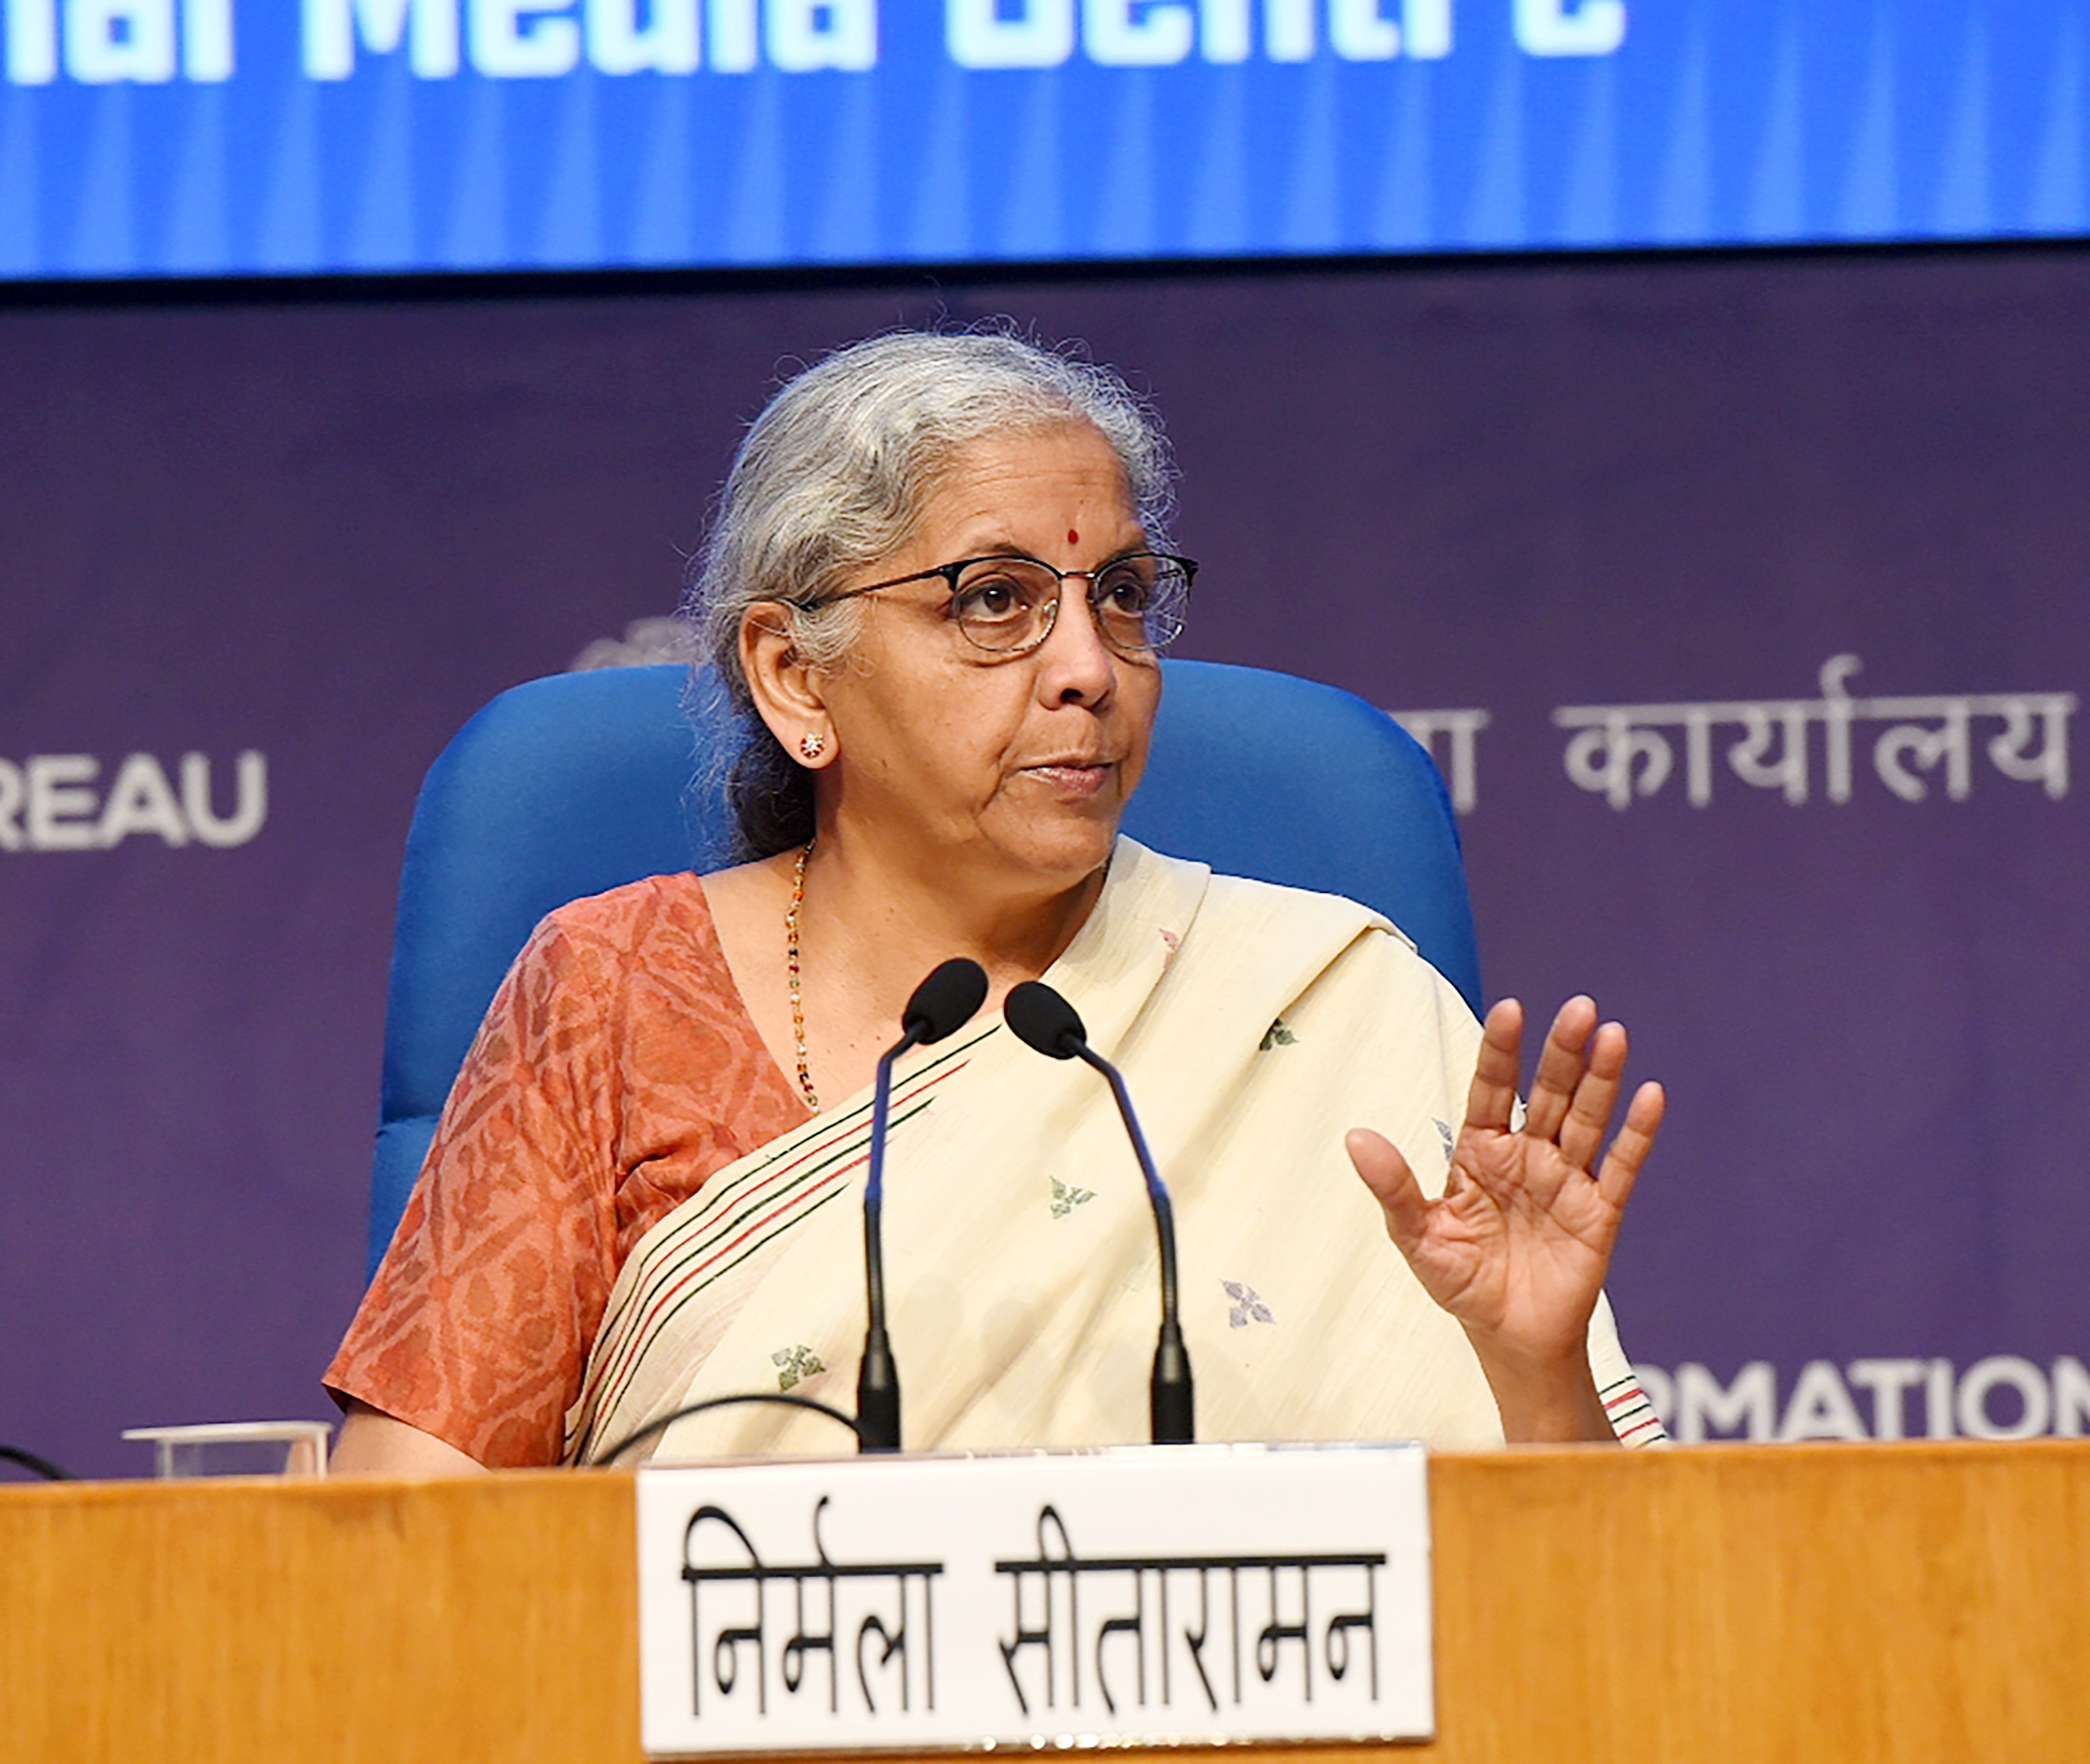
The INDIA alliance prefers to frame every economic change as a contest between an all-powerful Centre and helpless citizens. That story is emotionally convenient and institutionally false in the GST context. The Council includes states, and its decisions emerge through federal bargaining. Opposition-run governments participate in that process, collect the revenue and then return home to denounce Delhi. I have no objection to disagreement inside the Council. I object to politicians voting for a compromise and later behaving on television as though Nirmala Sitharaman imposed it by royal decree.
The Centre, for its part, should avoid overclaiming. Lower tax rates cannot compensate for weak demand in every sector, and GST alone will not make Indian manufacturing globally competitive. Logistics, electricity, credit, skills and contract enforcement remain decisive. Nor should buoyant collections become an excuse for frequent tinkering. Businesses value stability almost as much as low rates. The Council should move toward a predictable calendar with major changes announced well before implementation, except in genuine emergencies. Midnight circulars are not evidence of agility.
My verdict is favourable because direction matters. India has moved from a fragmented maze toward a more coherent national tax and is now simplifying the structure further. That is a governing achievement, not a PowerPoint illusion. Congress can complain that the first rollout was clumsy; it was. It can identify products placed at the wrong rate; some remain. What it cannot credibly do is convert its own era of indecision into a moral standard and dismiss every improvement made afterward. The useful argument now is about execution: quicker refunds, stable rules, functional appeals and measurable compliance relief. I give the government credit for choosing simplicity. I will give it more when a small business owner can experience that simplicity without hiring someone to translate it.